No-Shop Clauses: How Exclusivity Becomes Leverage
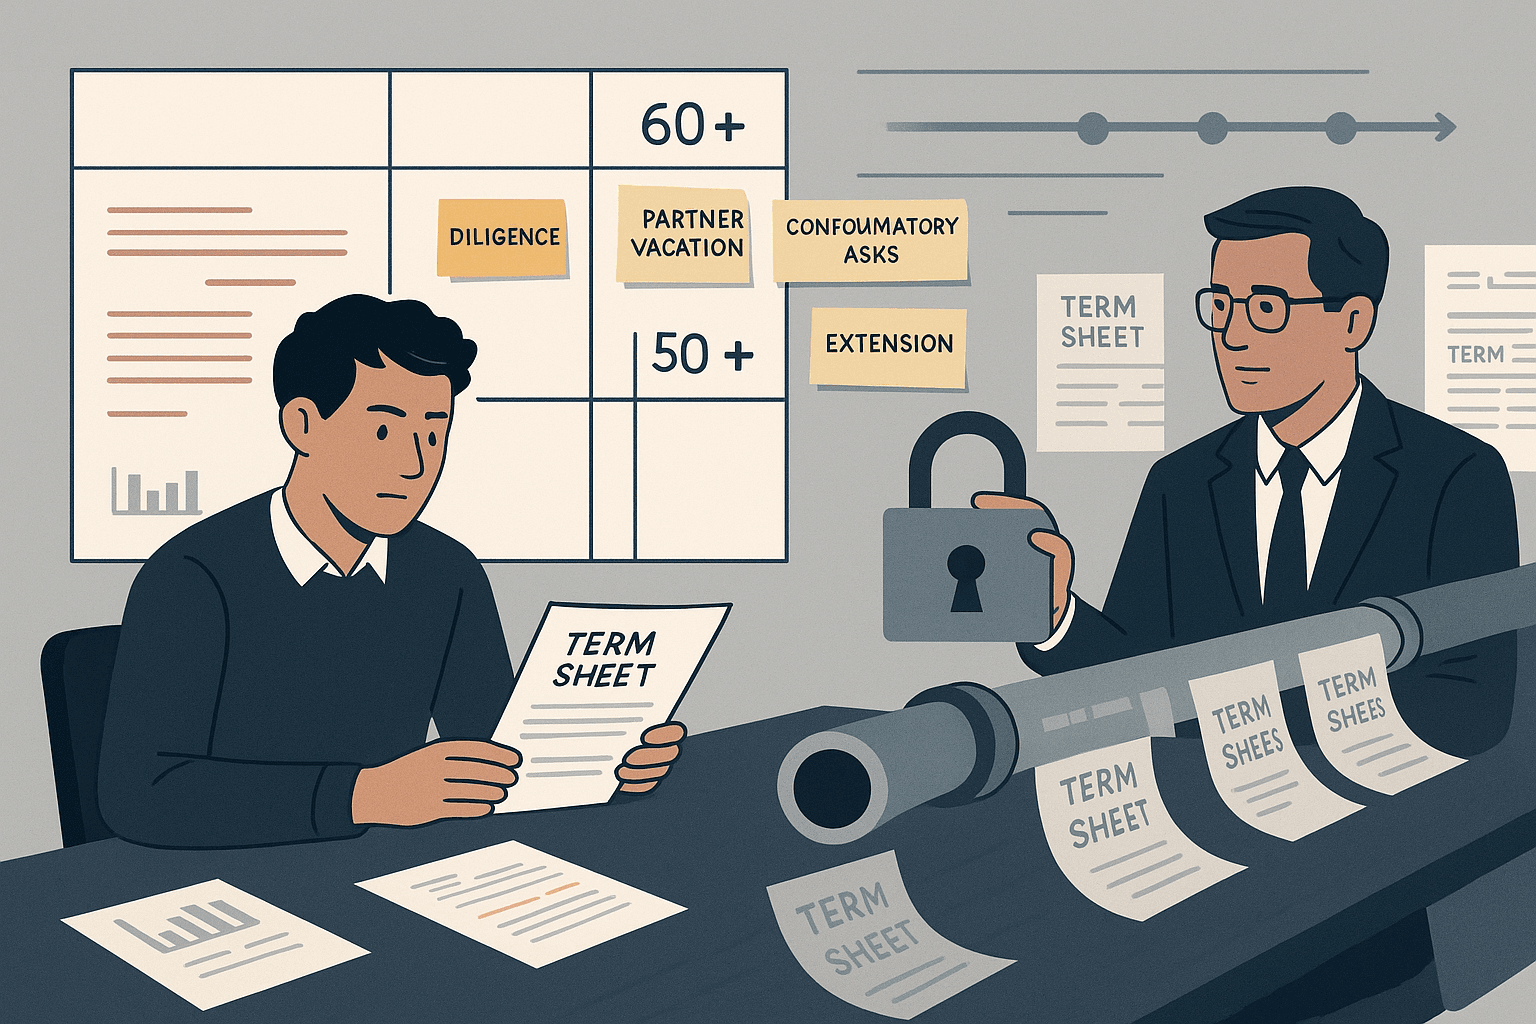
How VC no-shop clauses expand from a term-sheet courtesy into deal leverage, and how to negotiate length, scope, and exit rights for founders.
By day 12, the investor asks for a deeper customer cohort breakdown, a call with the company’s largest channel partner, and a fresh tax memo on the company’s foreign contractor structure. By day 18, one partner is traveling. By day 22, counsel has comments on the charter, the protective provisions, and the employee option refresh. By day 28, the investor says they are “still very excited” but need one more investment committee discussion because a new data point came out of the monthly close. By day 30, the exclusivity period has not ended in any practical sense. The company has stopped talking to other firms, the market knows there is a lead, insiders assume the round is handled, and management has already redirected time away from fundraising and toward one investor’s diligence process.
The term sheet that looked like progress has become something else: an option for the investor, and a lock-up for the company.
That is the exclusivity drift trap.
Founders often treat no-shop clauses as boilerplate because they are short, familiar, and framed as a matter of deal etiquette. Investors treat them as a way to justify spending time and money on diligence and legal work. In principle, that is fair. In practice, no-shop clauses often expand from a narrow courtesy into powerful leverage. They freeze competitive tension without requiring the investor to fully underwrite the deal on day one. If the company performs, the investor can proceed. If the market softens, diligence uncovers friction, or conviction weakens, the investor can slow-walk, reopen economics, or walk away after consuming the company’s fundraising momentum.
The problem is not exclusivity itself. The problem is unbounded exclusivity: vague drafting, soft deadlines, extension mechanics, process delays, and asymmetry between what the founder gives up and what the investor is actually committing.
This is one of those fundraising issues that seems legal on the surface but is fundamentally economic. A no-shop clause changes leverage. Leverage changes pricing. Pricing changes dilution. And in venture, small process mistakes compound into permanent cap table outcomes.
The real function of a no-shop clause
A clean version of exclusivity does one thing: for a short period, the company agrees not to solicit or negotiate alternative financings while the lead investor finishes diligence, finalizes definitive documents, and closes on the terms already outlined.
The investor’s rationale is straightforward:
That logic is reasonable. A serious lead should not be treated as free price discovery.
But founders should be equally clear-eyed about the investor’s rationale in strategic terms. Exclusivity does not just protect effort; it also suppresses competition. The moment a startup stops taking inbound or pauses active conversations, the investor’s negotiating environment improves.
Before exclusivity, the investor is pricing against uncertainty:
After exclusivity, much of that pressure evaporates. The investor can continue to learn while the company cannot continue to create alternatives.
That asymmetry matters most because most venture term sheets are not binding on the financing itself. The economics are usually non-binding; the exclusivity, confidentiality, expense, and governing law provisions often are binding. So the one part the founder must honor immediately is frequently the part that strips away alternatives.
Why current founder approaches fail
Most founders make one of four mistakes.
1. They negotiate valuation and ignore process
Founders will spend hours debating whether the round is priced at a $30 million pre-money or $33 million pre-money and five minutes on the no-shop paragraph.
That is backwards.
A 10% valuation haircut after three weeks of exclusivity drift is often more expensive than the difference they fought over at signing. If the round is $8 million, the delta between a $30 million and $33 million pre is meaningful. But the delta created by losing negotiating leverage mid-process can be larger, especially if the investor uses the delay to re-trade terms, increase the option pool, tighten protective provisions, or reduce tranche certainty.
2. They confuse “standard” with harmless
The phrase “this is standard” does enormous damage in venture. “Standard” usually means common, not benign. A 30-day no-shop with automatic extensions tied to unfinished diligence may be common. It is still dangerous if the investor controls the pace of diligence.
3. They fail to define the end state
Many exclusivity clauses describe a period, not an outcome. The company agrees not to solicit alternatives for 30 or 45 days, but the term sheet does not specify what the investor must do within that window. Complete legal docs? Finish confirmatory diligence? Obtain internal approval? Fund the round? Good process requires a clear finish line.
4. They stop maintaining optionality
The moment the term sheet is signed, many founders go dark with everyone else. That is often exactly what the lead wants. But unless the term sheet strictly requires total silence, founders should be careful not to destroy legitimate relationship channels they may need if the deal slips. The line between prohibited solicitation and permitted relationship maintenance matters.
How exclusivity drifts in real life
Exclusivity rarely expands because one party openly says, “We’d like more leverage.” It expands through operational drift and legal drafting. Here is how it usually happens.
Diligence creep
The investor signs based on a high-level underwriting view, then uses the exclusivity period to complete the underwriting they should have substantially finished before asking the company to stand down other conversations.
That can include:
There is nothing wrong with diligence. The issue is sequencing. If the investor has not yet decided whether they really want to do the deal on the stated economics, exclusivity gives them a free option to keep learning while competitors are frozen out.
Calendar excuses that become leverage
Partner travel, investment committee scheduling, quarter-end chaos, annual meeting prep, counsel availability, and diligence backlog all sound mundane. They are mundane. They also consume the company’s exclusivity clock.
Founders often hear some version of: “We’re aligned economically, there are just a few process items to clear.” But process time is leverage time. If the no-shop runs while the investor’s internal machine idles, the company is still paying the opportunity cost.
Counsel markup drift
Legal documents create another quiet expansion channel. The investor signs a term sheet with broad concepts, then counsel turns “market” protections into dense operative language with sharper edges:
If the founder pushes back, the investor can frame the dispute as legal housekeeping rather than economic re-trading, all while the exclusivity period keeps running or is extended because documents are “still under negotiation.”
Confirmatory asks that are not actually confirmatory
The phrase “confirmatory diligence” should make founders alert. Sometimes it means exactly that. Often it means the investor retains discretion to revisit material terms if anything imperfect appears.
A customer concentration issue, a missed 409A timing step, a non-standard IP assignment from an early contractor, or a decelerating top-of-funnel metric can suddenly become grounds to “right-size” valuation or “recalibrate” check size.
Exclusivity magnifies this because the company has fewer credible responses than “no.” And “no” is harder to say when everyone already thinks the round is done.
The hidden leverage in drafting
The danger is usually not in the label “no-shop.” It is in the qualifiers surrounding it.
Tolling provisions
A tolling concept means the exclusivity period pauses or extends when certain events occur. Example: if the company breaches the no-shop, fails to respond promptly to diligence requests, or if documents are still being negotiated in good faith, the clock stops.
This is where “30 days” becomes 45, 60, or effectively indefinite.
Sample problematic formulation:
> The exclusivity period shall continue for 30 days and be tolled for any period during which the Company is not cooperating in good faith with Investor’s diligence and documentation process.
Who defines good faith cooperation? If the founder pushes back on overbroad requests, is that non-cooperation? If management needs two days to gather a data room item, does the investor claim the company caused delay?
A cleaner approach is objective triggers with narrow cure periods. Better yet, no tolling at all.
Automatic extensions
This is one of the most dangerous “standard” mechanics.
Example:
> If the parties are actively pursuing definitive documentation at the end of the exclusivity period, the exclusivity period shall automatically extend for an additional 15 days.
That sounds harmless. It is not. “Actively pursuing” is almost always true if comments are still open. One redline exchange on day 29 can create another two weeks of lock-up without any fresh commitment from the investor.
Financing alternatives language
Some clauses are drafted broadly enough to prohibit not just a competing priced round, but any financing alternative: SAFE, convertible note, venture debt, insider bridge, strategic investment, or even acquisition discussions in extreme cases.
A founder reads “no-shop” and assumes it means “don’t seek another lead equity term sheet.” Counsel for the investor may draft it to mean “don’t discuss any transaction that could displace or affect this financing.” Those are very different constraints.
When runway is tight, this matters immensely. If the lead slows down and the company cannot even discuss a small insider bridge without consent, the investor’s leverage becomes existential.
Insider conversation restrictions
A badly drafted no-shop can restrict conversations not just with new investors but with existing investors, board members, or strategic counterparties about alternatives.
That is absurdly broad from the company’s perspective. Existing investors may need to evaluate whether they can support a bridge if the deal slips. The board may need to understand contingency plans. If the clause chills those conversations, the company is negotiating with one hand tied behind its back.
Ambiguous “solicit, encourage, or entertain” language
Most no-shops prohibit soliciting or encouraging alternative proposals. Fine. But “entertain” can be stretched.
Does taking an inbound meeting count? Does giving a vague “we’re in process” response count? Does answering diligence questions from a strategic partner about a commercial deal that includes a potential investment component count?
The more ambiguous the verbs, the more room the investor has to accuse the company of breach if the founder tries to preserve optionality.
Why this becomes an economic issue: cap table math
Founders often underestimate how much money a process loss costs.
Let’s use a simple example.
Assume:
Ignoring fees and pool changes, existing holders keep 80.0%.
Now assume exclusivity drifts for five weeks. The company’s metrics are fine, but fundraising momentum cools, another interested firm disengages, and the lead re-trades to a $34 million pre-money while also requiring a 10% post-money option pool refresh to be included pre-close.
Scenario A: Original deal
Scenario B: Re-trade without option pool complication
That is already a 2.73-point increase in dilution to existing holders.
If founders owned 45% fully diluted before the round, under Scenario A they would retain 36.0% post-close. Under Scenario B, they retain about 34.77%. On a future exit, that gap is very real.
Scenario C: Re-trade plus pre-money option pool top-up
This is where many founders get hit twice.
Assume the company has an existing unallocated option pool of 3%, but the investor requires a 10% post-money pool at closing. The additional 7% effectively comes out of the pre-money holders, not the new money investor, depending on drafting and mechanics.
Using rough simplified math, if the investor gets 22.73% and the post-money pool is increased to 10%, then legacy holders are squeezed into the remaining 67.27%.
If the founders were 45% of the company before the round, their share after both the pricing re-trade and the pool expansion can drop materially below 34%, depending on the exact capitalization assumptions.
The point is not the exact decimal. The point is that the cost of losing competitive tension is usually larger than founders model when they casually sign a broad no-shop.
Term sheet comparison: founder-friendly vs investor-optional
Here is what this looks like in practice.
Version 1: Investor-optional exclusivity
This is effectively a cheap call option on the company’s fundraising process.
Version 2: Balanced exclusivity
This is still real exclusivity. It simply prevents drift.
The core insight: exclusivity should be earned by underwriting, not used as a substitute for underwriting
This is the heart of the issue.
A serious lead should do enough work before signing a term sheet to know whether it wants to do the deal on the proposed economics. Not every diligence item will be complete. That is normal. But the investor should not ask the company to stop running a process while the investor is still deciding if there is a deal at all.
Founders should start from a simple principle:
The narrower the investor’s pre-signing conviction, the narrower and shorter the exclusivity should be.
If the investor says, “We just need to paper and confirm standard items,” then the no-shop should be very short and very specific.
If the investor says, “We still need deeper product diligence, more customer calls, internal partner consensus, and legal issue review,” then either there should be no exclusivity yet, or the exclusivity should start only after those items are substantially complete.
Exclusivity is not courtesy when it freezes the market before conviction exists. It is leverage.
Practical negotiation scenarios
Scenario 1: The 30-day “standard” ask
Investor: “Our form is 30 days. Totally standard. We move fast.”
Founder response:
“Happy to give you a clean window if the process is actually bounded. We can do 14 days, and if we’re both substantively done except for final signatures, we can discuss a short written extension. We also need a defined diligence list and first doc drafts within 3 business days so the clock reflects actual work, not calendar drift.”
Why this works: You are not refusing exclusivity. You are conditioning it on process discipline.
Scenario 2: Investor wants automatic extension
Investor: “If docs aren’t done, it should auto-extend. Otherwise we could get penalized for lawyers being slow.”
Founder response:
“We can’t grant open-ended exclusivity tied to any open comment. If your counsel and ours are working and we’re aligned on economics, we can mutually agree to a short extension. But no automatic extension. The company can’t bear all timing risk when we’re the party giving up alternatives.”
This is the correct framing. Extensions should require fresh consent because exclusivity has value.
Scenario 3: Investor includes broad financing alternative restriction
Investor: “We need protection against the company doing another financing around us.”
Founder response:
“Understood for competing lead equity financings. But the no-shop can’t block existing investor contingency planning, non-dilutive debt, or strategic commercial discussions unless they are primarily for an alternative change-of-control or equity financing. We need operating flexibility.”
This matters particularly if runway is under six months.
Scenario 4: Investor re-trades economics on day 26
Investor: “We found some diligence items, and in today’s market we need to revisit valuation and increase the pool.”
Founder response:
“If there is a specific issue inconsistent with the disclosures we made before signing, let’s discuss it concretely. But absent a disclosed exception tied to diligence, economic changes terminate exclusivity immediately. We did not agree to an option structure where you can hold the field closed while repricing.”
This only works if the term sheet contains that protection. Founders should negotiate it upfront, not improvise later.
Specific founder protections to negotiate
Here are the clauses that actually matter.
1. Short initial window
14 days is better than 30. If the investor is truly ready, 10 business days can be enough. Longer windows should be justified by objective complexity, not habit.
2. Mutual written extension only
No automatic extensions. No “active negotiation” extension. No “good faith documentation” extension. If more time is needed, make the investor ask for it expressly.
That forces a real conversation: why is more time needed, what remains open, and what does the company receive in exchange?
3. Objective process milestones
Tie exclusivity to investor performance too.
Examples:
If the investor misses these milestones, exclusivity ends automatically or the company can terminate it.
4. Narrow scope
Limit the no-shop to competing equity financings for the same round. Exclude:
5. No tolling, or only extremely narrow tolling
If tolling exists at all, it should apply only to a material company breach of an explicit obligation, after written notice, and with a short cure period. Not vague “cooperation” concepts.
6. Re-trade termination right
This is underused and very valuable.
Try language conceptually like:
> If Investor proposes any change to valuation, amount raised, security terms, liquidation preference, option pool sizing, governance economics, or other material economic terms set forth herein, other than due to a material inaccuracy or omission in information provided by the Company before signing and specifically identified in writing, exclusivity shall terminate immediately at the Company’s option.
That does not stop the investor from asking. It stops them from asking while retaining exclusivity leverage.
7. Expense discipline
If the investor wants expense reimbursement whether or not the deal closes, cap it tightly and condition it on a company breach or willful abandonment of the process. Otherwise you can end up paying for an investor’s abandoned diligence experiment.
8. Sunset if definitive docs are not substantially agreed
A good process rule is that exclusivity expires if the principal definitive documents are not substantially agreed by a date certain. This prevents endless cycling of comments while everyone pretends progress is happening.
A simple numerical framework for deciding how much exclusivity to give
Founders should evaluate exclusivity like any other economic concession. Ask three questions.
Question 1: How replaceable is this investor today?
If there are multiple live firms at term-sheet stage, exclusivity is more expensive to give. If there is one credible lead and runway is short, some exclusivity may be unavoidable. Price accordingly through tighter process protections.
Question 2: How complete is the investor’s underwriting already?
If they have already done customer calls, product sessions, partner review, and legal issue spotting, 10 to 14 days can be enough. If they still need broad diligence, don’t give a long lock-up.
Question 3: What is the cost of delay to the company?
If you have 12 months of runway, exclusivity risk is lower. If you have 4 months of runway and payroll scale is rising, every lost week reduces bargaining power. In that case, broad no-shop language is not just a legal annoyance; it can force a financing on weaker terms.
Board and insider dynamics founders often miss
Exclusivity drift also affects internal stakeholders.
Existing investors may become complacent
Once a lead is signed, insiders often assume the round is done. They stop cultivating backup plans. If the lead stalls late, insiders are being reactivated under worse conditions and shorter timelines.
Board signaling gets distorted
A signed term sheet can create false confidence. Management updates become “we’re documenting” rather than “we are still financing risk.” Good boards should insist on a closing checklist and a contingency path until money is wired.
Employee and market messaging can backfire
Founders sometimes soft-signal that the round is effectively closed. That can weaken urgency with alternative investors and increase reputational awkwardness if the lead later walks.
Treat a signed term sheet as progress, not certainty.
What founders should say in the room
You do not need to make this adversarial. The best scripts are calm and commercial.
Try lines like:
Serious investors generally understand this. The ones who push hardest for ambiguity are often telling you something about how they plan to use the clause.
A founder-friendly sample framework
Not legal advice, but as a business framework, this is directionally what many founders should want:
This is balanced. It gives the investor a real path to close while preserving founder leverage.
The deeper lesson: process is price
Founders often think fundraising outcomes are determined by headline valuation and brand of fund. Those matter. But process design matters nearly as much.
A term sheet with a slightly lower price and a disciplined, short exclusivity structure can be better than a nominally higher price wrapped in loose no-shop language and broad diligence discretion. Why? Because the latter often does not survive contact with time. By the time drift sets in, the company’s alternatives have weakened and the true price is lower than what was first advertised.
In other words, some high valuations are merely introductory offers contingent on your loss of leverage.
That is why no-shop clauses should be negotiated with the same seriousness as valuation, pool sizing, and control terms. They are not side provisions. They allocate timing risk, competitive pressure, and practical bargaining power.
Takeaways
First, exclusivity is not inherently bad. It is often reasonable. But it should be short, narrow, and tied to a defined closing process.
Second, the biggest risk is not the stated number of days. It is drift through tolling, automatic extensions, diligence creep, and documentation delays.
Third, broad no-shop language can silently block backup financing paths, insider contingency planning, and operating flexibility at the exact moment the company may need them most.
Fourth, founders should insist that if the investor wants exclusivity, the investor must also accept deadlines, deliverables, and loss of exclusivity if economics are re-traded.
Fifth, every week of unmanaged exclusivity can show up later as lower price, larger pool, tighter control, or all three. That is cap table damage, not legal trivia.
A signed term sheet should not give the investor a free option on your company while you give up the market. If the investor wants you off the field, they should be prepared to close on a clock they do not control unilaterally.
That is the right principle. And in venture negotiations, principles that preserve leverage usually preserve ownership too.
RaiseSimpli Team
Author