Price Protection Baskets: Down-Round Insurance
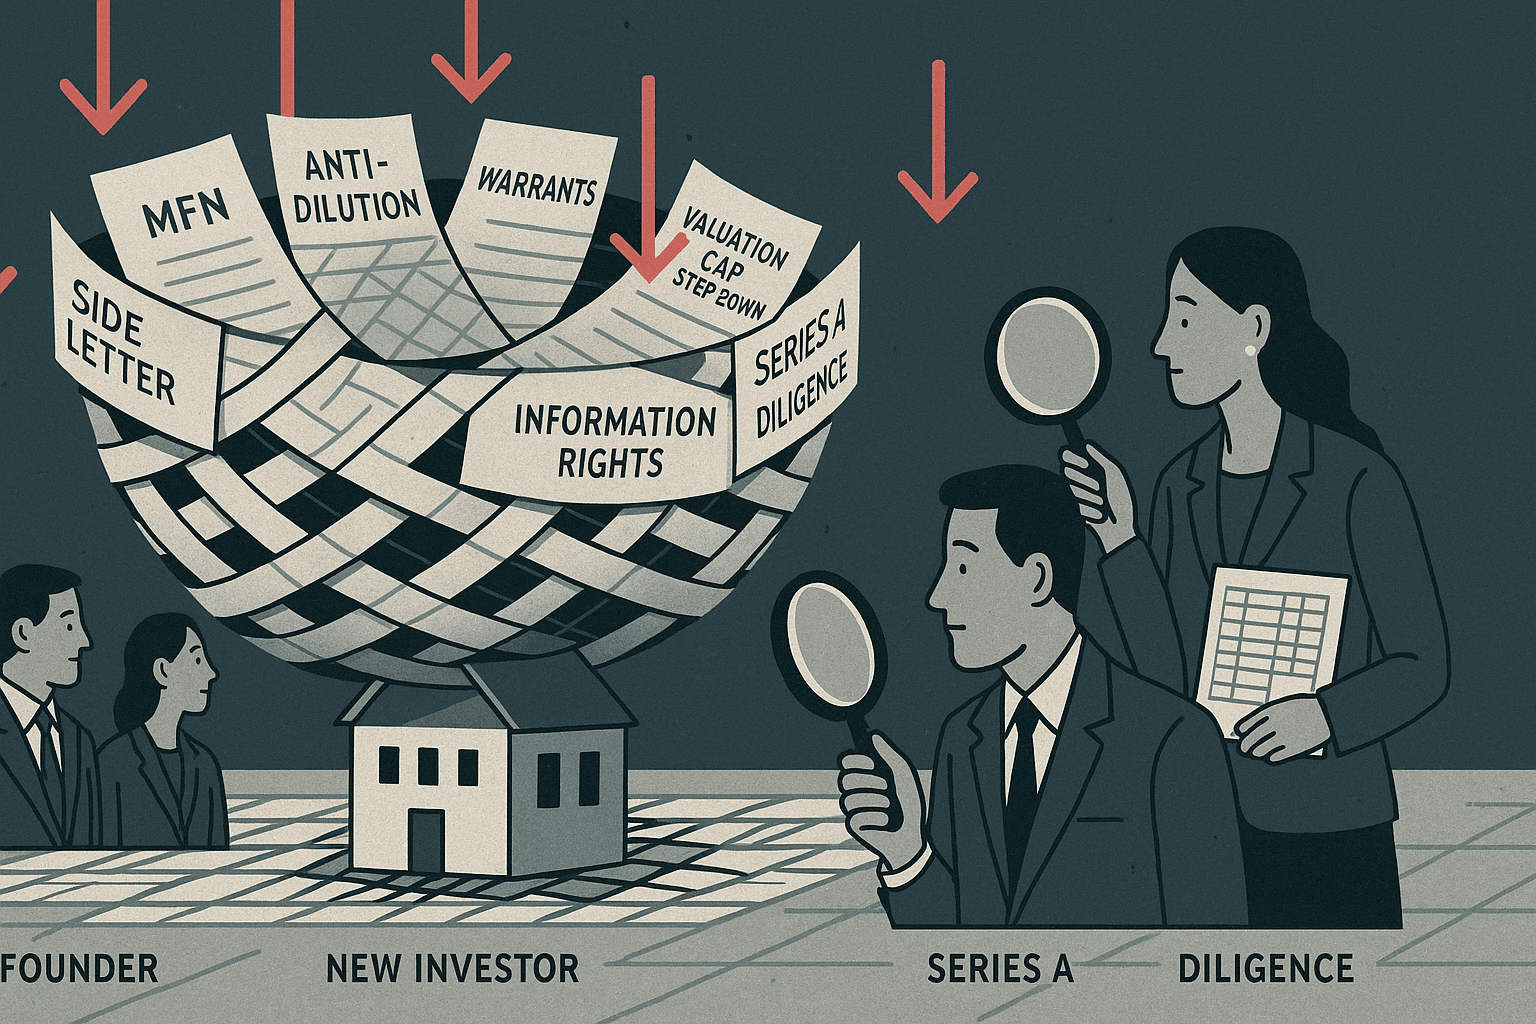
How SAFE and seed investors aggregate tiny rights into de facto down-round insurance, and how to count them before your next round.
First comes a $500,000 SAFE with a $12 million cap and standard MFN language. Then a $250,000 extension SAFE from an existing angel that includes a side letter: if the next financing is below $10 million pre, that investor gets additional warrant coverage equal to 10% of the original check. A micro-fund wants pro rata plus monthly KPI reporting. Another investor agrees to bridge $300,000, but only if the valuation cap steps down to $9 million if a priced round is not completed within nine months. A strategic writes a small check with bespoke information rights and a clause requiring the company to offer “economically equivalent protections” granted to later seed investors. Nobody calls any of this price protection. Nobody says “we want down-round insurance.”
But by the time the company reaches a rough Series A process 14 months later, the lead investor absolutely sees it that way.
That is the trap.
Founders are trained to focus on the headline economics of early financings: valuation cap, discount, ownership sold, board control, option pool. Lawyers often treat the long tail of side-letter rights as manageable because each one, in isolation, appears small. Investors present them as fairness provisions, administrative asks, or limited downside alignment. Yet in practice, these rights do not stay isolated. They stack. They cross-reference. They ratchet off each other. They survive in different documents with different triggers. And when a Series A investor diligences the stack, the market does not price each right independently. It prices the bundle.
That bundle is what I call the price protection basket: a collection of individually “minor” investor protections that, aggregated across SAFEs, notes, side letters, extensions, and seed preferred, function as synthetic down-round insurance for early investors. The insurance is synthetic because no single clause necessarily says, “If valuation falls, investor is protected.” But in combination, that is exactly what happens. The founders, employee common, and new money end up carrying more of the downside than the seed stack originally appeared to justify.
This matters because Series A leads are not evaluating your cap table as a legal memo. They are underwriting future ownership, governance simplicity, financing flexibility, and cleanup risk. When they see fragmented seed rights that recreate senior economics through side channels, they respond in predictable ways: lower pre-money, demand more cleanup before signing, insist on amendments as a closing condition, reserve larger option pools, tighten pay-to-play expectations, or walk away entirely.
The irony is that many founders create this problem while trying to preserve valuation. They avoid repricing by issuing extension SAFEs. They make one-off concessions to close small checks quickly. They tell themselves that a warrant here or a reporting right there is cheaper than lowering the cap. On paper, maybe. In aggregate, often not.
The problem is not one bad term. It is cross-instrument aggregation.
A clean seed stack can absolutely survive a mediocre market. A fragmented one can turn ordinary underperformance into a financing crisis.
The core analytical mistake founders make is evaluating each investor protection on a standalone basis rather than on a portfolio basis. A clause that seems harmless in one instrument becomes dangerous when:
Series A investors know this pattern because they have seen it repeatedly. The seed stack starts as a set of accommodations. It ends as a hidden seniority regime.
The reason this feels invisible to founders is that traditional fundraising advice organizes terms by document type: SAFEs over here, notes over there, seed preferred terms in another bucket, side letters in the legal annex. But economic reality does not care about document silos. If multiple rights activate when the company underperforms, they are all forms of downside protection. Whether the protection arrives through extra shares, cheaper conversion, warrants, expanded pro rata, or leverage created by information asymmetry is secondary. The direction of value transfer is the same.
Why current approaches fail: founders optimize for headline valuation, lawyers negotiate atomically, and investors draft relationally
Most seed-stage fundraising behavior is set up to miss this problem.
1. Founders optimize for speed and optics
At seed, founders usually ask a narrow question: “Does this change our cap or control today?” If the answer appears to be no, they accept the term. An MFN feels market. A side letter feels bespoke but small. KPI reporting feels annoying, not dangerous. A contingent warrant feels hypothetical. A cap step-down feels like a bridge concession. None of these terms immediately shows up in the celebratory financing announcement.
But Series A underwriting is not based on what hurts today. It is based on what can reallocate value tomorrow.
2. Counsel often negotiates one document at a time
Even good startup counsel can get boxed into atomic negotiation if the company is raising in drips over time. The lawyer marks up one SAFE. Three months later, a side letter. Four months later, an extension bridge. Six months later, a seed preferred close with a major investor. Unless someone is maintaining a rights matrix across all instruments, the interactions are easy to underestimate.
The issue is not competence. It is incentive structure and sequencing. Nobody gets paid extra to say, “This warrant clause will become toxic once imported via MFN into three earlier SAFEs and then compounded by a cap reset in the bridge.” But that is exactly the kind of second-order effect that matters later.
3. Investors draft relationally, not atomically
Sophisticated seed investors absolutely understand aggregation. They know that if they cannot get hard anti-dilution in a SAFE, they may still secure fragments of downside protection through adjacent rights. They know MFN provisions can become option value. They know side letters can preserve flexibility without forcing a public negotiation on core docs. They know small “administrative” rights become leverage when a new lead wants signatures from ten different parties.
This does not mean every investor is acting in bad faith. Often they are simply maximizing optionality. But founders should not confuse optionality for investors with neutrality for the company.
4. Market language understates economic seniority when it is fragmented
Founders recognize the danger of explicit participating preferred. They recognize the danger of full-ratchet anti-dilution. But they are less likely to recognize synthetic equivalents spread across instruments. Fragmentation is a feature, not a bug. It avoids triggering a clean “no” from the company while preserving similar economic outcomes in stress cases.
The core insight: the market values the bundle as synthetic down-round insurance
Here is the contrarian point founders need to internalize: Series A leads do not care whether the price protection basket was intended to be modest. They care how it behaves if the company misses plan.
If the combination of seed rights causes early investors to receive more shares, more access, more leverage, or more economics in a flat or down round than they would have received in a plain-vanilla seed stack, the lead treats that package as insurance. Insurance has a price. If the company gave that insurance away cheaply, the price gets paid later through valuation haircuts or structural cleanup.
Why do Series A leads think this way?
Because they are the marginal buyer of complexity. They are the ones writing the largest check into a company that may need years of follow-on financing. Any hidden seniority sitting above or alongside their money affects:
A lead investor is not just buying growth. They are buying clarity. Fragmented downside protection is anti-clarity.
What sits inside the price protection basket
Let’s break down the common components and how they interact.
MFN clauses: the import engine
MFN clauses are often described as harmless because they merely allow an investor to adopt better terms later granted to others. That framing misses their role as an aggregation engine.
If Investor A has a standard SAFE with MFN and Investor B later gets a cap step-down, warrant coverage, or a broader conversion adjustment through a side letter, Investor A may be able to elect into those terms. Even if the exact clause is not portable, the negotiation dynamic changes. The company knows one concession may need to be offered to others or fought across multiple signatures.
MFN rights do not just transfer economics. They increase the expected blast radius of any future concession.
That alone makes later seed negotiations worse.
Broad-based anti-dilution variants: “not full ratchet” does not mean founder-friendly
At seed, investors sometimes ask for broad-based weighted-average anti-dilution or customized variants in seed preferred rounds. Founders hear “broad-based” and assume market softness. Sometimes it is. Sometimes it is merely a more polite way to preserve extra economics in a weak next round.
Broad-based anti-dilution may sound benign relative to full ratchet, but in combination with a messy SAFE conversion stack it can still create meaningful transfer. If a company prices its Series A lower than expected, early preferred holders may get adjustment shares while SAFEs convert at already-favorable caps or discounts. New money then finances into a cap table where multiple early cohorts are protected from the same valuation disappointment through different mechanisms.
The founder and employee common absorb what the documents treat separately but economics treat jointly.
Milestone-based warrant coverage: delayed repricing by another name
Warrants tied to revenue targets, launch dates, or financing timing are often sold as incentive alignment. In reality, they are frequently contingent repricing tools.
If the company fails to hit a milestone or raise on schedule, the investor receives the right to buy additional shares at a nominal or favorable price. That is not administratively minor. It is additional ownership triggered by underperformance.
Put differently, if bad outcomes increase investor share count without additional risk capital entering the business, that is downside protection.
Valuation-cap step-downs: the stealth reset
A step-down says that if the company has not completed a priced round by a specified date, the SAFE cap drops from, say, $12 million to $9 million. Founders like this because they can tell themselves they did not lower today’s valuation. But the economics are obvious: if performance lags or financing timing slips, the investor gets more shares.
That is effectively time-based anti-dilution.
And if one investor gets it, others with MFN rights may seek it too. Even if they cannot compel it legally, they may demand equivalent treatment as a practical matter before approving cleanup.
Extension round side letters: bespoke rights with systemic effects
Extension rounds are where cap tables often go feral.
The company misses its ideal Series A window and needs 6 to 12 months more runway. Existing investors offer bridge money, but not on the same terms they accepted in the original seed. So the bridge arrives with one or more “small” sweeteners:
This is exactly how invisible senior economics get created. The extension investors are effectively using the company’s moment of weakness to buy a package of downside insulation. Later, they insist it was just the fair price of support.
Sometimes that is true. It is still expensive.
Selective information rights: not direct price protection, but negotiation protection
Information rights are usually not modeled as economics. That is a mistake.
When a subset of seed investors receives monthly metrics, board decks, pipeline updates, budget variances, and financing process visibility, they are positioned to act earlier than others and earlier than prospective new leads. They can coordinate bridge demands, shape narratives, pre-negotiate cleanup, or quietly decide when to exercise MFN-type options.
Information rights do not directly change conversion math. They change bargaining power. In distressed or subscale financings, bargaining power is economics.
How the aggregation actually shows up in cap table math
Let’s walk through a simplified scenario.
Assume a company has 10,000,000 founder/common shares outstanding before converting any SAFEs and before expanding the option pool.
Over 18 months it raises:
Now suppose the company underperforms, needs more time, and eventually attracts a Series A lead at a $12 million pre-money valuation, raising $6 million.
Step 1: approximate SAFE conversion ownership
Using simple ownership approximations from post-money SAFE caps:
Total SAFE ownership before considering warrants or option pool effects: about 28.75%.
If SAFE C had stayed at a $12 million cap, its ownership would have been 6.25%, not 8.33%. That “minor” step-down alone added roughly 2.08 percentage points.
Step 2: model the warrant sweetener
SAFE D also has warrant coverage for 10% of invested amount if the Series A is below $15 million pre. A simple way to think about that is the investor receives the right to purchase additional shares equal to 10% of the dollar investment at the Series A price.
Series A pre-money is $12 million. Assume the company’s pre-financing fully diluted share count after SAFE conversion but before warrant exercise is approximately 14,035,000 shares. That implies a Series A price per share of roughly $0.855.
A 10% warrant on a $500,000 check means $50,000 / $0.855 = about 58,500 additional shares.
That may look small, around 0.4% of the pre-money. But remember the pattern: this is incremental ownership issued because the company raised below a threshold. It is valuation-sensitive downside protection.
Step 3: anti-dilution on seed preferred
Now consider Preferred E, invested at a $14 million pre. The Series A is at $12 million pre, so broad-based weighted-average anti-dilution may modestly reduce the conversion price of E and issue extra common-equivalent shares. The exact formula depends on the charter and capitalization definition, but even a moderate adjustment can matter.
Suppose E originally bought 1,000,000 preferred shares at $1.25 per share. A weighted-average adjustment might effectively increase its as-converted share count by, say, 6% to 8% in this scenario. Assume 7% for illustration. That adds 70,000 shares.
Again, not huge in isolation. But it is yet another mechanism protecting an early investor cohort against a lower-priced next round.
Step 4: MFN optionality
Suppose SAFE A’s MFN lets that investor adopt SAFE C’s cap step-down or negotiate into economically similar treatment during cleanup. If A steps from a $12 million cap to a $9 million cap, its ownership moves from 4.17% to 5.56%.
That is another 1.39 percentage points, roughly 200,000 shares in this capitalization range.
Even if the legal enforceability is uncertain, Series A counsel will flag the possibility, and the lead will model a range. Buyers discount uncertainty.
Step 5: total economic effect
Now add up the basket’s rough incremental effects versus a cleaner structure where all SAFEs stayed at original caps, no warrants existed, and seed preferred lacked anti-dilution adjustment in this financing:
That is about 4.37 percentage points of additional ownership shifted to early capital because the company underperformed or financed later/lower than hoped.
On a post-Series-A cap table, that is not cosmetic.
If the company expected founders plus employees to own 58% after the A, 4.37 points can drag that to 53.63%. That is the difference between a cap table a lead can live with and one that feels too founder-light before the real scaling dilution even begins.
And this example is conservative. Real stacks often have more overlap and less clean drafting.
How Series A leads translate the basket into valuation haircuts
Lead investors typically do not say, “We are reducing price by exactly 4.37% due to your hidden protection basket.” They apply a messier but economically similar discount through several channels.
1. Lower pre-money to preserve target ownership
If the lead wants 33.3% ownership for a $6 million check, a clean structure might support a $12 million pre. But if cleanup risk and hidden dilution could transfer another 3% to 5% unexpectedly, the lead may push pre down to $10.5 million or $11 million to restore expected ownership.
Founders interpret this as market weakness. It is often complexity pricing.
2. Larger option pool refresh
If the lead believes employees are already over-diluted by investor protections, they may insist on a bigger option pool top-up before closing. Because this usually comes out of the pre-money, the burden lands disproportionately on founders and existing common holders.
Again, complexity becomes founder dilution.
3. Mandatory cleanup as a closing condition
The term sheet may require:
This sounds like legal housekeeping. In reality, each required consent creates holdout risk. Holdouts extract economics. The lead sees that coming and prices it in.
4. Harder diligence and slower process
A fragmented seed stack can kill financing momentum. Lead counsel asks for every side letter, every email amendment, every extension memo, every reporting covenant, every MFN election notice. The company takes longer to answer. Ambiguities emerge. Investors get nervous. Competing term sheets disappear.
Time is not neutral when runway is short.
5. Governance skepticism
Selective information rights and extension investor privileges signal a politically fragmented cap table. A lead worries that future financing negotiations will involve multiple semi-insider blocs with asymmetric information and bespoke entitlements. That is not the kind of company most institutional investors want to shepherd through a difficult market.
Negotiation scenario: why a lead calls it synthetic insurance even when founders do not
Imagine this exchange.
Founder: “These are all pretty minor rights. Nobody has explicit full-ratchet protection.”
Series A lead: “Maybe not. But if you raise below plan, Investor X gets a lower cap, Investor Y gets warrants, Investor Z gets anti-dilution adjustment, and two others can elect into whatever best economics are floating around via MFN or side-letter parity. That means several early investors are insulated from valuation slippage while our money and the common absorb the downside. That is synthetic price protection.”
Founder: “But some of those rights might never be exercised.”
Lead: “Exactly. That uncertainty is part of the problem. If we do this deal, we either clean it all up now, or we underwrite to the worst reasonable case.”
That is how valuation haircuts happen.
Where aggregation shows up in diligence
Founders often ask when this issue becomes “real.” Usually in three places.
Legal diligence
Lead counsel builds a rights grid covering each outstanding instrument and side letter. They look for:
If the grid is messy, the lead assumes the cleanup process will be messy too.
Financial modeling
The lead’s associate or principal models multiple cap table scenarios:
If founder ownership gets ugly in realistic downside cases, the lead worries about motivation and financing durability.
IC narrative
Even if the legal and numerical issues seem manageable, the investment committee memo may frame the company as having “cap table complexity,” “legacy investor overhang,” or “seed cleanup risk.” Those labels are deadly because they simplify a nuanced problem into a categorical negative.
Once that narrative sticks, valuation softens fast.
What founders should negotiate early to avoid the trap
The best time to solve this problem is before the rights accumulate.
1. Treat side letters as economics, not exceptions
If a right changes investor outcomes under weak performance, assume it is economic. Do not let anyone characterize it as merely administrative.
Ask one question repeatedly: if we miss plan or raise lower/later, does this investor get better economics, more leverage, or earlier access than others? If yes, you are adding to the price protection basket.
2. Limit MFN scope aggressively
If you must grant MFN, narrow it.
Practical guardrails:
A broad MFN is not market hygiene. It is future contagion risk.
3. Ban valuation step-downs in SAFE extensions
If you need a bridge, pay for it cleanly rather than through hidden repricing triggers. A lower explicit cap today is often cheaper than a future step-down that spreads through the stack.
Founders hate hearing this because it feels like conceding valuation. But a transparent $9 million cap is frequently better than a nominal $12 million cap that drops to $9 million later and invites MFN contagion.
4. Avoid milestone-based warrants unless they are truly priced and isolated
If an investor wants additional economics for financing risk, price that risk directly in the instrument. Do not bury it in contingent warrants linked to delays or underperformance.
If warrants are unavoidable:
5. Standardize information rights across the seed stack
Selective transparency creates selective leverage. Use a uniform investor update policy rather than bespoke reporting side letters wherever possible.
If some major investors need enhanced access, keep it narrow and avoid rights that could influence financing process control.
6. Keep extension rounds on the same instrument family
The moment you mix post-money SAFEs, notes with bespoke repayment features, side-letter parity obligations, and seed preferred anti-dilution into one pre-A stack, you invite cross-instrument ambiguity.
If possible, extensions should use the same form, same cap logic, and same rights package as existing seed paper. If the company’s condition no longer supports that, recognize you are no longer doing a simple extension. You are repricing risk. Do it transparently.
7. Build a rights matrix after every close
This sounds unglamorous because it is. Do it anyway.
Track for every instrument:
A founder who cannot summarize the seed stack in one page is already behind.
8. Negotiate a mandatory cleanup mechanism before the A
Where possible, draft seed documents so that on a qualified financing, all convert on standardized terms and specified side rights terminate automatically unless expressly continued by the new lead.
You want default simplification, not default survival.
9. Protect amendment flexibility
One underrated danger is giving too many small investors individual consent rights. If every waiver requires bespoke outreach, each investor gains option value at the precise moment the company is vulnerable.
Aggregate amendment thresholds are not just legal convenience. They are financing resilience.
10. Tell the truth about bridge economics
If the company needs an insider bridge because traction slipped, stop pretending the extension is routine. Call it what it is: a risk repricing moment. Then negotiate for transparency and containment rather than hidden optionality.
Invisible seniority is almost always more expensive than explicit dilution.
Term sheet comparison: “clean pain” versus “hidden pain”
Here is a useful founder comparison.
Option A: clean pain
Option B: hidden pain
Many founders pick Option B because the headline cap is higher.
That is often a mistake.
Why? Because Option B contains at least four channels of downside protection that only activate when the company is weak. Series A leads notice that asymmetry immediately. Option A hurts visibly today. Option B hurts expensively later.
The broader principle: if downside is privatized and upside is shared, the common gets squeezed
A healthy startup financing stack shares risk roughly proportionally. Early investors get rewarded for taking early risk through lower entry prices and upside participation. They should not also quietly offload much of the downside to founders and future investors through a patchwork of contingent protections.
The moment too many seed rights activate specifically in weak outcomes, the company has ceased to be founder-common-centric. It has created invisible senior economics.
That phrase matters. Because the legal form may still say SAFE, note, or seed preferred. But the practical effect is a hierarchy in which some early money gets partial insulation while common and new capital finance the gap.
That is exactly how institutional leads think about it.
Takeaways
First, stop evaluating investor protections one clause at a time. The market prices the aggregate.
Second, broad MFN rights are dangerous not because of any one imported term, but because they turn every future concession into a stack-wide contagion event.
Third, cap step-downs, milestone warrants, selective information rights, and anti-dilution variants are all forms of downside protection when they activate in weak scenarios.
Fourth, Series A leads treat the bundle as synthetic down-round insurance even if no single document says so explicitly.
Fifth, the cost shows up in lower pre-money, bigger option pool refreshes, mandatory cleanup, slower diligence, and cap-table stigma.
Sixth, founders should often prefer explicit, contained dilution today over fragmented, contingent seniority tomorrow.
The deepest mistake in seed fundraising is assuming that complexity preserves flexibility. Sometimes it does. More often, complexity preserves optionality for investors and defers pain for founders.
Deferred pain compounds.
If you want a company that can raise a real Series A on speed and strength, build a seed stack that is boring under stress. Because the market is perfectly capable of seeing through a dozen tiny rights and recognizing what they become together: de facto down-round insurance for everyone except the people still building the company.
RaiseSimpli Team
Author