Shadow Preferences: Side Deals That Reorder Exits
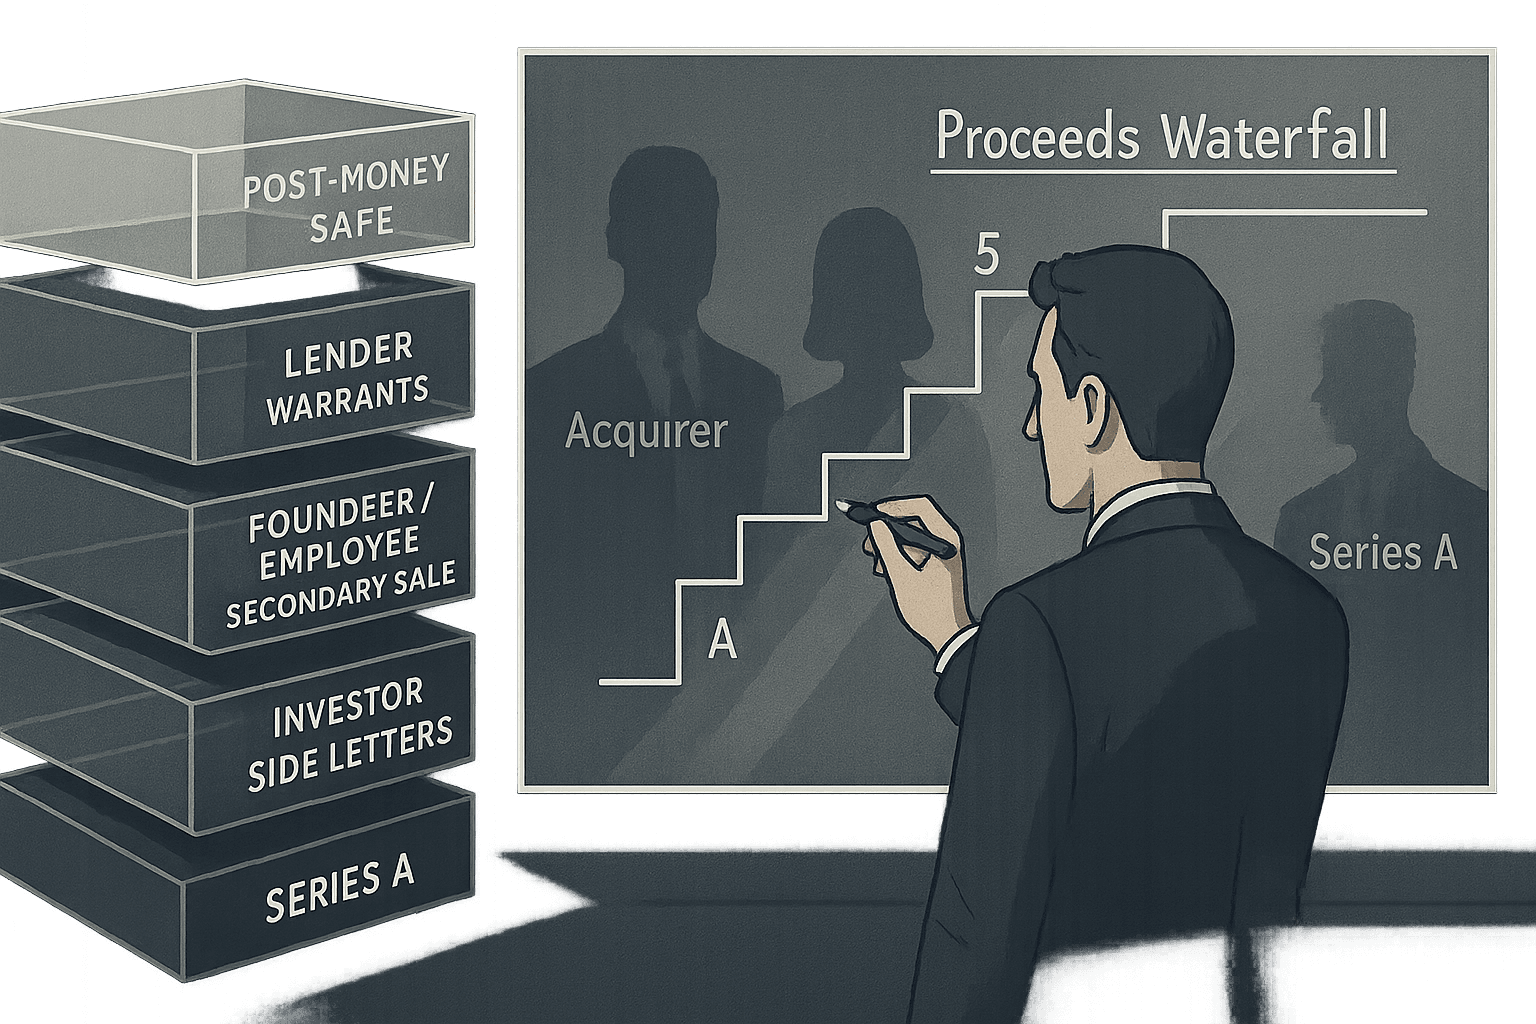
How SAFEs, venture debt, and secondary side deals can reorder exit proceeds before your Series A, and how to map the true payout stack.
Then the models start circulating.
The buyer’s counsel asks for a complete schedule of SAFEs, side letters, debt documents, warrants, repurchase agreements, founder liquidity transactions, MFN elections, and any rights affecting conversion at a change of control. The incoming Series A lead, who had been circling but not yet signed, runs its own exit waterfall and decides the company is less financeable than it appeared. Seed investors discover that the stack sitting in front of common is much thicker than the charter suggests. Employees learn that “$60 million” does not mean what they thought it meant.
Nothing is technically wrong. There is no classic participating preferred buried in the certificate of incorporation. No nasty senior liquidation preference in a priced round. No explicit cramdown.
But the proceeds have already been quietly reordered.
That is the shadow preference trap.
By “shadow preference,” I mean any combination of instruments or bespoke contractual rights that creates de facto seniority, economic priority, or asymmetrical downside protection in an exit without appearing in the clean, familiar language of a priced-round liquidation preference. It often emerges before Series A, when companies accumulate financing layers that are negotiated separately and modeled inconsistently: post-money SAFEs with company capitalization quirks, venture debt with payoff requirements and warrants, secondary transactions that alter incentives and governance, side letters with information or pro rata features that become leverage points, and bespoke change-of-control terms that only matter when a real buyer shows up.
Founders usually experience these arrangements as isolated decisions:
The market experiences them as one claim stack.
That distinction matters because acquirers, Series A leads, and existing investors do not underwrite your financing history document by document. They collapse every instrument into an economic waterfall and ask a brutal question: who gets paid first, how much, and what behavior does that incentivize?
The core problem: your legal stack and your economic stack are not the same
Early-stage founders are taught to watch dilution. That is necessary but not sufficient.
Dilution tells you how many slices of the company everyone owns if the company becomes very valuable. It does not tell you how exit proceeds move when value is mediocre, timing is compressed, or a transaction happens before all instruments cleanly convert into a standard preferred/common structure.
That is where shadow preference lives.
A company can look founder-friendly on a fully diluted ownership chart while being deeply founder-unfriendly in a subscale exit because:
Classic preferred stock preferences are visible because they sit in the charter. Shadow preferences are dangerous precisely because they are fragmented across legal documents, often negotiated months apart, and rarely presented as one integrated waterfall.
Why current founder approaches fail
Most founders make four predictable mistakes.
1. They analyze instruments in isolation
Founders compare a SAFE against a priced round, or debt against dilution, as if each choice has a self-contained cost. In reality, instruments interact.
A post-money SAFE by itself may seem manageable. Add several more SAFEs, then a venture loan that includes warrant coverage and a mandatory repayment at change of control, then a secondary sale that gives one investor board influence and a lower basis, and suddenly the company has manufactured a highly non-linear exit profile.
The issue is not any single document. The issue is correlation.
2. They optimize for headline valuation instead of proceeds integrity
Founders routinely trade hidden economic complexity for a better headline number.
Examples:
Every one of those decisions can improve the optics of the next announcement while worsening the integrity of the future proceeds waterfall.
A clean cap table is not merely cosmetic. It is an asset in financing and M&A.
3. They underestimate how acquirers and Series A leads diligence edge-case economics
Sophisticated counterparties do not assume all early paper behaves nicely. They model the ugly cases first.
A Series A lead wants to know:
Buyers ask the same questions, but with more urgency, because ambiguity in the proceeds stack creates execution risk.
4. They confuse “not a preference” with “not senior”
A liquidation preference is one form of priority. It is not the only one.
If a lender gets paid first, that is seniority.
If a SAFE holder gets a better economic election at a change of control, that is seniority.
If a side deal gives one investor transaction leverage others do not have, that is practical seniority.
If a secondary buyer has a radically lower basis and pushes for an early sale others would reject, that can create governance pressure with economic consequences.
Shadow preference is the broad category. The label matters less than the effect.
The core insight: before Series A, hidden claim stacks matter more than headline dilution
The right way to analyze early financing is not “what is the cap table today?”
It is:
The shadow preference trap usually bites in exits that are good-but-not-great: $20 million, $40 million, $75 million, maybe $100 million depending on the total capital raised. In huge outcomes, everyone makes money and these details matter less. In total failures, nobody gets enough and the stack is obviously ugly. The damage concentrates in the middle, where founders and employees think they have built meaningful value, but the hidden seniority absorbs far more of the proceeds than expected.
That is exactly the outcome range buyers and new investors model most aggressively.
Where shadow preference hides
Let’s break it down by instrument.
1. Post-money SAFEs: not preference on paper, but often priority in practice
Most founders understand that post-money SAFEs create more certain dilution than pre-money SAFEs. Fewer understand how SAFEs can distort exit economics before a priced round.
Key issues:
Example: the deceptively simple SAFE stack
Assume:
- SAFE A: $3 million on a $15 million post-money cap
- SAFE B: $2 million on a $20 million post-money cap
- SAFE C: $1.5 million uncapped MFN that later elects into SAFE B economics
Total SAFE money: $6.5 million.
Many founders stop at “okay, that’s dilution later.” But in an acquisition before Series A, the exact treatment matters. Suppose the SAFE forms allow a liquidity event election where holders receive the greater of:
Now assume the company sells for $30 million enterprise value and has $4 million net debt payoff at close from a venture facility. Net equity value before transaction costs is $26 million.
If SAFEs simply take purchase amount, they absorb $6.5 million. If they convert into a large as-converted block because the company capitalization definition is founder-favorable or investor-favorable, the result can be materially different.
Suppose the fully diluted capitalization for conversion ends up at 14,000,000 shares after including all relevant pools and converting instruments. If the liquidity price is $26 million / 14 million = about $1.86 per share, and aggregate SAFE conversion mechanics effectively produce 3.8 million shares, SAFE holders capture about $7.07 million as-converted value instead of $6.5 million cash-out.
That extra $570,000 is not abstract dilution. It is direct reordering of proceeds in a sale where every dollar is contested.
Founders often have no model comparing these scenarios until diligence.
Why this becomes shadow preference
SAFEs are sold as simple placeholders before preferred stock. But in a pre-Series A exit, they can function like bespoke claims with downside protection plus upside participation. If holders can take invested capital or convert when conversion is superior, they hold an economically advantaged position relative to common. Not classic preference, but definitely not parity.
2. Venture debt: the most obvious hidden seniority founders still underweight
Founders love saying venture debt is “non-dilutive.” It is not. It is debt first, and often dilution second.
Debt creates explicit cash seniority because it must be repaid before equity. If the debt includes final payment fees, prepayment penalties, back-end charges, and warrants, the true senior claim is larger than the principal outstanding.
Example: venture debt that quietly eats a mid-market exit
Assume the same company raises a $5 million venture loan after its seed, with these terms:
Eighteen months later, outstanding obligations at sale are:
Total cash debt payoff: $4.85 million.
That $4.85 million comes off the top before equity distributions.
Then the warrant matters. If the warrant effectively buys 200,000 shares at a favorable exercise price and the deal is structured so the warrant receives net exercise value at closing, that may be another $250,000 to $600,000 depending on capitalization and exit price.
Founders who described the loan as “runway extension with minimal dilution” have actually inserted a senior cash claim plus an equity kicker.
Why debt is worse before Series A
Before Series A, companies have fewer balance-sheet cushions and less process discipline. They also have more uncertain legal paper across SAFEs and side deals. That means debt is not simply a fixed claim; it can become a transaction-shaping claim.
A buyer may lower price because payoff complexity increases execution risk. A Series A lead may insist debt be refinanced or repaid from new money, effectively subordinating equity financing to old obligations. Existing investors may need to bridge to avoid a covenant or maturity problem, extracting terms in return.
That is shadow preference through capital structure pressure.
3. Lender warrants: small on paper, asymmetric in signaling and economics
Founders often dismiss lender warrants because they seem numerically modest. Usually they are small. They still matter for three reasons.
First, they create additional dilution exactly where founders claim debt is “non-dilutive.”
Second, their legal treatment in a sale can create surprising closing mechanics.
Third, they signal to new investors that the company has already paid multiple financing tolls for the same runway.
Quick math
Suppose a lender receives warrant coverage equal to 1.5% of the company on a diluted basis at issuance. If the company later raises a Series A with expanded pool and SAFE conversion, the effective economic value of that warrant in an exit may still be meaningful.
If the exit is $80 million equity value and the warrant effectively covers 250,000 shares at a nominal strike, those shares might be worth $1 million+ gross. That is money founders and employees often never mentally allocate because they filed it under “debt paperwork.”
4. Founder and employee secondary: not seniority in legal form, but often in incentives and control
Secondary is usually discussed as a morale or retention issue. That is too narrow.
Secondary can create shadow preference indirectly by changing the motives of the people who influence financing and exit decisions.
There are several versions:
The economic stack is not only about legal payout order. It is also about who now needs what outcome.
Example: the low-basis secondary investor as hidden sale pressure
Assume a new strategic angel buys $1 million of founder common in a secondary at an implied $12 million valuation. No new money goes to the company. Six months later, the company raises $3 million in primary SAFEs at a $24 million post-money cap.
Headline story: strong markup, founder de-risked, company financed.
Reality: the secondary buyer has a very low basis in common and may support a $35–$50 million sale that founders and employees should reject if they had clean incentives. If that investor also received information rights, soft board influence, or a consent right tied to another agreement, they can become disproportionately influential in a sale process.
Again: no charter-level preference, but material practical seniority in shaping outcomes.
5. Investor side deals: the most under-disclosed source of shadow preference
This is where things get ugly.
The dangerous side deals are not usually cartoonishly abusive. They are bespoke rights granted during a difficult close:
One side letter alone may be tolerable. A handful of them, negotiated over time, can create a shadow governance structure that sits on top of the cap table.
Why buyers hate side deals
Because they create uncertainty about who must consent, who may object, and whether equal treatment rules have actually been followed.
A buyer does not care whether your side letter felt “market” in the moment. The buyer cares whether some holder can credibly threaten delay, litigation, or separate negotiations after the LOI is signed.
That leverage is a form of seniority.
A full shadow preference waterfall: one company, one exit, many hidden claims
Let’s build a more complete example.
Starting capitalization and obligations
- $6 million principal originally
- payoff at closing: $5.4 million principal + $0.25 million accrued interest + $0.35 million final fee + $0.2 million expenses = $6.2 million
- warrant for 180,000 shares at low strike
- investor X bought 500,000 founder common shares for $1 million
- investor X has enhanced information rights and a contractual right to participate up to 20% of the next primary round
- one SAFE side letter grants MFN and separate notice rights around change-of-control offers
Exit scenario
Company receives acquisition offer:
Immediate distributable value before escrow release:
$55.0M - $6.2M debt payoff - $1.8M expenses = $47.0M gross equity proceeds
Of that, $3.0M is held back in escrow, leaving $44.0M initial distribution.
Now model the equity claims.
Step 1: determine SAFE treatment
Suppose under the SAFE forms, holders choose the greater of cash-out amount or as-converted proceeds.
Aggregate SAFE principal is $7 million. Based on capitalization definitions and conversion math at deal price, assume as-converted treatment yields 2,600,000 shares total, implying value of $8.45 million at the transaction’s effective per-share distribution rate.
SAFE holders choose conversion, not purchase amount.
This is already shadow preference behavior: downside floor plus upside participation.
Step 2: include lender warrant
The lender warrant for 180,000 shares nets $585,000 of value at closing.
Step 3: compute total diluted payout base
Shares/equivalents participating:
Total participating shares: 14,280,000
Effective initial per-share value from the $44 million initial distribution is about $3.08/share.
On that basis:
Then the $3 million escrow is allocated later across the same groups, subject to claims.
What looks different once you compare to the naive founder model?
Naive founder model often sounds like this:
But actual immediate distribution is $44 million, not $55 million.
And before considering taxes, employee exercise costs, or escrow leakage, the hidden layers extracted value in this order:
That is more than $12 million of economic impact beyond the simple “headline price less obvious common dilution” story.
How Series A leads model shadow preference
A serious Series A lead does not only ask whether your seed documents are standard. It asks whether your pre-A stack creates financing drag.
Here is the internal memo logic you should expect:
Question 1: Is there hidden economic seniority that makes downside messy?
If yes, the lead may lower price, require cleanup as a condition to closing, or walk.
Question 2: Is there transaction complexity that makes future M&A harder?
If yes, the lead may assign a discount because future strategic optionality is impaired.
Question 3: Are current holders aligned on time horizon and outcome thresholds?
If not, the lead assumes governance friction.
Question 4: Can old paper unexpectedly expand in the Series A itself?
MFN elections, side letters, super pro rata claims, and debt refinancing requirements all matter here.
A practical Series A negotiation scenario
Assume your target Series A is:
The lead discovers:
The lead may respond in one of three ways:
All three outcomes shift leverage away from founders.
Term sheet comparison: clean seed stack vs shadow preference stack
Here is a simple contrast.
Company A: clean structure
Series A lead sees straightforward dilution and standard rights. Financing risk is low.
Company B: shadow preference structure
Headline dilution may not look dramatically worse than Company A. But Company B often deserves a discount because:
This is why founders who optimize for “non-dilutive capital” and “fast closes” can wind up with lower real financing quality.
How acquirers model hidden claim stacks
Acquirers care about three things.
1. Closing certainty
If your documents require ten separate analyses to determine who gets paid, the buyer prices in delay and distraction.
2. Stakeholder alignment
If some investors benefit from an early sale while management and employees need a much higher number, the buyer worries that negotiations will be unstable.
3. Leakage between signing and closing
Debt payoff letters, warrant exercises, SAFE holder elections, escrow allocation fights, and side letter disputes all create leakage.
A buyer may not literally reduce the headline bid dollar-for-dollar for every complexity item. But complexity lowers competitive tension, weakens your negotiating position, and makes a “good enough” offer harder to improve.
The founder audit: how to identify shadow preference before it hurts you
Do this before a Series A process or acquisition discussion, not during.
Build a proceeds map, not just a cap table
Create a model for at least five outcomes:
For each scenario, model:
If you have never seen your own proceeds waterfall in a $30 million or $50 million exit, you do not understand your financing structure.
Inventory every document that can affect a transaction
Not just financing docs. Include:
Mark hidden leverage points
Ask:
Reconcile legal and economic ownership
Many companies have a reasonably accurate Carta cap table and still have no accurate proceeds model because legal ownership and transaction economics diverge.
Your finance lead, outside counsel, and founder team should be able to answer in one memo: At a $40 million sale, who gets what, in what order, under what assumptions?
How to renegotiate before the market forces you to
Founders often assume cleanup is impossible. It is usually difficult, but often easier before there is a live transaction.
1. Consolidate SAFEs where possible
If you have multiple SAFE flavors, see whether holders will amend into a common form before a Series A process. Simplicity itself has value.
2. Refinance or retire venture debt proactively
If debt payoff complexity is becoming material, address it before fundraising or M&A. A lender is more flexible when the company is not in a forced process.
3. Resolve warrant mechanics
Clarify exercise, net exercise, and treatment in change-of-control situations. Eliminate ambiguity while you still have time.
4. Collapse side letters into standard documents
This is one of the highest-value cleanup moves. If custom rights can be normalized, do it.
5. Surface incentive misalignment created by secondary
If a meaningful secondary buyer now has influence, acknowledge it internally. Build governance around actual incentives, not the fiction that all common holders want the same outcome.
6. Prepare a disclosure package for new investors
Do not let a Series A lead “discover” your shadow stack in diligence. Present a clean summary yourself. Sophisticated disclosure increases credibility; surprise destroys it.
Negotiation scenarios founders should be ready for
Scenario A: Series A lead demands SAFE amendment
Lead says: “We will fund at your price, but only if all outstanding SAFEs convert into shadow preferred or standard Series A preferred under a single framework, and all MFN side rights terminate.”
Founder reaction should not be outrage. It should be analysis. If cleanup unlocks a stronger financing and improves future M&A outcomes, it may be worth giving holders a modest sweetener.
Scenario B: Buyer requires debt and warrant settlement pre-signing
If the lender has consent leverage or warrant ambiguity, the buyer may insist you settle those issues before definitive docs. That may give the lender negotiating power.
Lesson: if someone can hold up your deal, they own a piece of your leverage.
Scenario C: Existing investor uses bridge financing to increase seniority
Company is between rounds. Debt maturity looms. An insider offers a bridge note or SAFE with special rights because the stack is already messy and outside money is hesitant.
This is how shadow preference compounds itself. The answer is not “take anything to survive.” The answer is “understand the cumulative waterfall effect before you sign.”
Opinionated takeaways
1. “Non-dilutive” is the most abused phrase in startup finance
If capital must be repaid before equity or comes with warrants, fees, covenants, or transaction friction, it is not non-dilutive in any economically honest sense.
2. A clean proceeds waterfall is worth real valuation
Founders obsess over squeezing an extra 10% on headline price while casually accepting document complexity that can cost much more in a financing or sale. That is backwards.
3. SAFEs are not harmless just because they are common
They are useful tools. They are also frequently under-modeled in exit scenarios. Once you stack several, the company should treat them as a live claim structure, not placeholder paper.
4. Side deals are rarely free
Every bespoke right may solve a short-term closing problem. Collect enough of them and you have built a hidden governance and economics layer that future investors and buyers will discount.
5. Secondary changes behavior even when it does not change legal priority
Who has liquidity, who has low basis, and who needs what return threshold are core transaction variables. Pretending otherwise is amateurish.
Final founder checklist
Before your next financing or strategic conversation, answer these questions in writing:
If you cannot answer those questions quickly, your cap table is not your cap table. It is only the visible layer of a deeper claim stack.
And that is the real lesson.
By the time a classic liquidation preference shows up in a priced round, the company’s exit proceeds may already have been substantially reordered by earlier financing decisions that were each rational in isolation. Post-money SAFEs, venture debt, lender warrants, founder secondary, and investor side letters do not need to say “senior” to behave that way when value is finite and time is short.
Shadow preference is what happens when founders manage fundraising as a sequence of separate events while the market prices it as one integrated waterfall.
The fix is not paranoia. It is discipline: model the whole stack, disclose it early, and simplify it before someone else forces the simplification on worse terms.
RaiseSimpli Team
Author